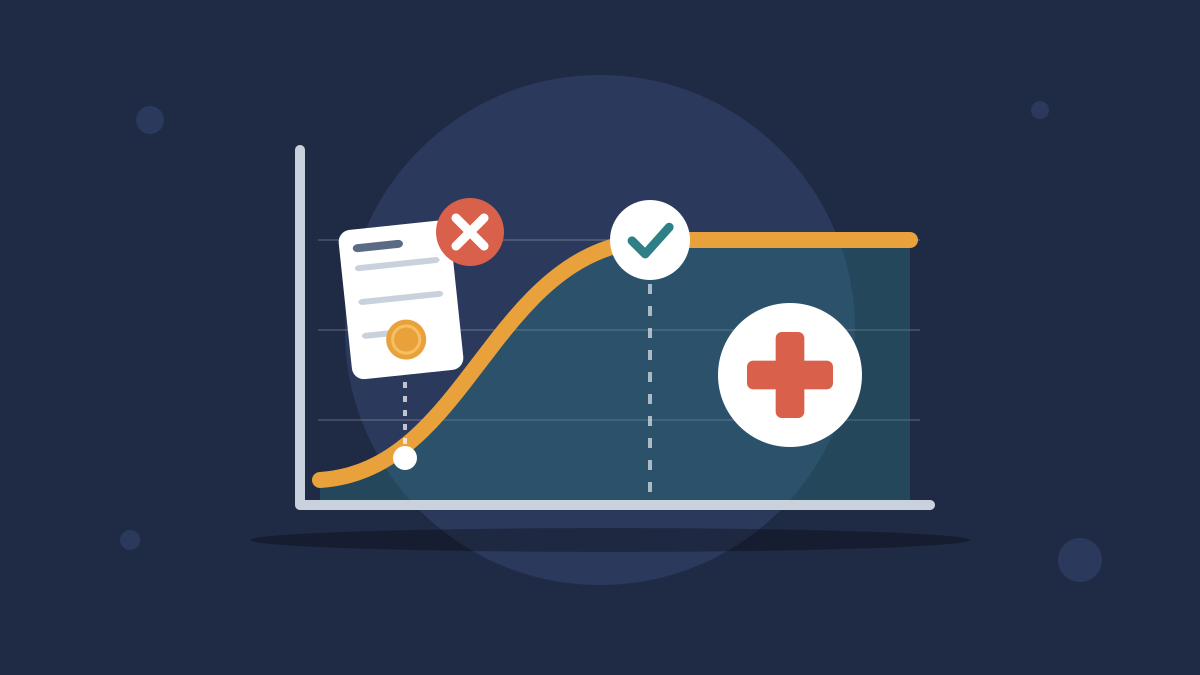
Maximum medical improvement, or MMI, is the point at which an injured person’s condition has stabilized and is not expected to improve further with additional treatment. It does not mean you’re fully healed — it means you’re as healed as you’re going to get, and any remaining limitations are likely permanent.
MMI is a medical judgment with major legal consequences. It’s the moment a case shifts from “how will this injury heal?” to “what will this injury cost for the rest of my life?” — and it changes what insurers can do in a workers’ comp claim.
MMI in a Personal Injury Case: Don’t Settle Before It
Until you reach MMI, nobody knows what your injury will ultimately cost. A back injury that might resolve with therapy or might require surgery can’t be fairly valued. Insurers know this — which is why early settlement offers arrive before MMI, when your future costs are still invisible. Because a settlement release is final, accepting before MMI means any later surgery or lasting limitation comes out of your pocket. Reaching MMI first lets your attorney build the full compensatory damages picture, including future care.
MMI in Pennsylvania Workers’ Compensation
In workers’ comp, MMI is the gateway to an impairment rating — and that’s where it can cost you:
- After 104 weeks of total disability benefits, the insurer can request an Impairment Rating Evaluation (IRE).
- The IRE can only be done once you’ve reached MMI. The evaluating physician determines a whole-body impairment percentage.
- If the rating is below 35%, your status changes from total to partial disability — and partial benefits are capped at 500 weeks.
- Your weekly check doesn’t change immediately, but the clock on how long you can receive it starts running.
This 104-week / 35% framework comes from Act 111 of 2018, passed after the Pennsylvania Supreme Court struck down the prior system. Our full guide to MMI and impairment ratings in Pennsylvania workers’ comp explains how to prepare for an IRE and challenge a bad rating.
Who Decides You’ve Reached MMI?
Your treating physician is the primary voice, but it’s a judgment call and doctors disagree. In workers’ comp, the insurer may send you to an Independent Medical Examination (IME) by a doctor of its choosing, who may declare MMI sooner — or declare you recovered entirely. An IME finding of MMI or full recovery is one of the most common tools used to cut off benefits, and it can be challenged with your own doctor’s evidence.
MMI Is Not the End of Treatment
Reaching MMI doesn’t mean medical care stops. Ongoing pain management, therapy to maintain function, and future surgeries can all remain reasonable and necessary. In workers’ comp, medical benefits continue after MMI; what changes is the disability status. Watch for the insurer treating MMI as a reason to stop or reduce your benefits — it isn’t one. Our workers’ compensation attorneys handle IRE and IME disputes regularly.
Frequently Asked Questions
No. MMI means your condition has stabilized and isn’t expected to improve significantly with more treatment. You may still have pain, limitations, and a need for ongoing care. It marks the point where remaining problems are considered permanent, not the point where they’re gone.
Generally no. Before MMI, the full cost of your injury — including future surgery or permanent limitations — is unknown, and a settlement release is final. Insurers often make early offers for exactly this reason. Reaching MMI first allows your future damages to be properly valued.
After 104 weeks of total disability benefits, the insurer can request an Impairment Rating Evaluation once you’re at MMI. If your whole-body impairment is rated below 35%, your status shifts to partial disability, which is capped at 500 weeks. Medical benefits continue; the duration of wage-loss benefits becomes limited.